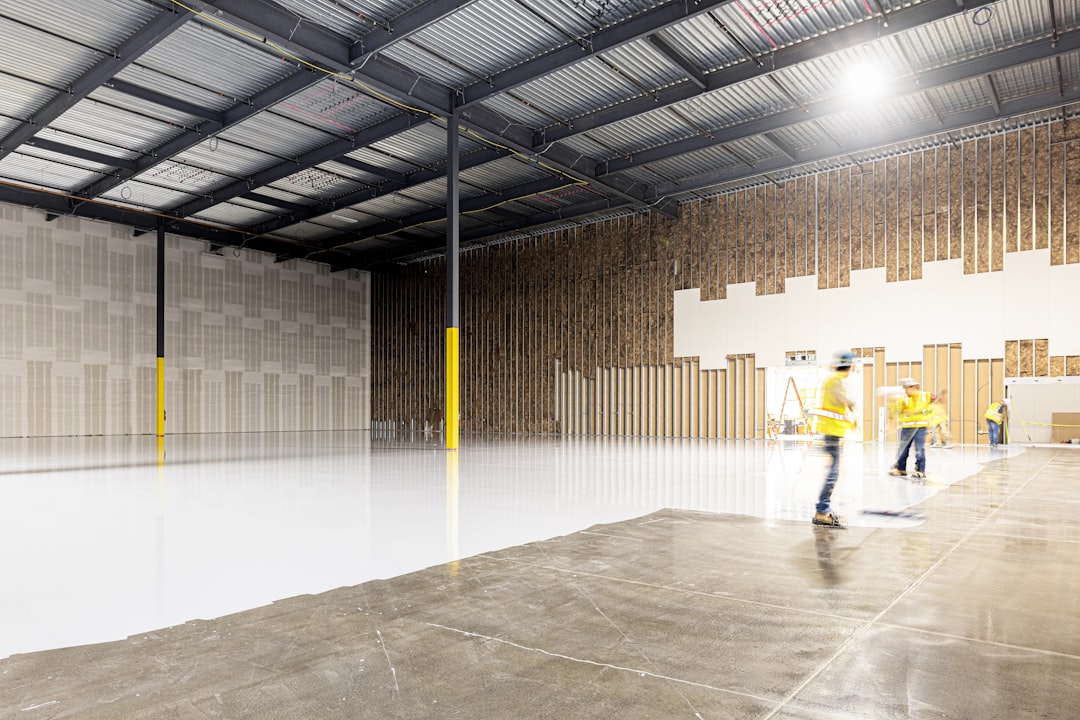
Storage units in New York City now rank among the most supply-constrained, high-occupancy real estate assets in the United States, and the transaction data confirms that serious money has taken notice.
Why NYC creates permanent demand for storage
New York City’s structural supply problem is the foundation of this investment thesis. The average New Yorker has about 2.4 square feet of self-storage per person, versus roughly 6 square feet nationally, even though NYC apartments are among the smallest in the country. Facility occupancy stays above 90% in New York, and demand far outpaces the limited supply. That gap does not close on its own.
With over 83% of the U.S. population residing in urban areas as of 2024, urbanization drives self-storage demand. Urban populations in cities like New York are projected to grow further, where limited living space and high housing costs push residents toward external storage. The city adds people faster than it adds storage capacity.
NYC added about 451,000 square feet of new storage in 2025, yet that was only 1.9% of existing inventory, not nearly enough to close the gap, which keeps occupancy above 90% and rates firm. For investors, a market with structural undersupply and a captive renter base is not an accident. It is a feature.
The transaction numbers investors need to know
The scale of capital flowing into storage units nationally tells you everything about institutional conviction. Self-storage property sales nearly doubled, with $6 billion trading hands through November 2025 versus $3 billion in 2024, per MMCG Invest. That is not speculative money. That is patient capital looking for durable cash flow.
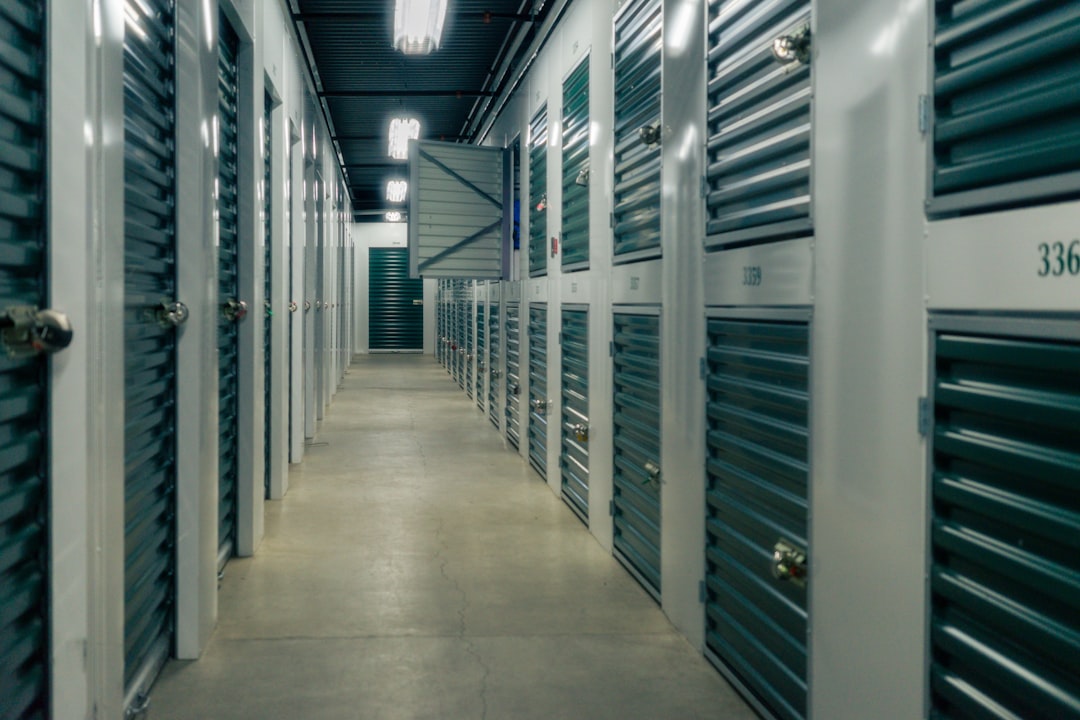
Queens led the nation in self-storage sales volume, surpassing $100 million in transactions in 2024, with Brooklyn also ranking fourth at $60 million. Queens topped the national list in total sales volume at over $100 million, with prices hitting $389 per square foot. These are not Sun Belt numbers. These are New York numbers, and they reflect a market where sellers have pricing power.
Consistent occupancy levels, month-to-month lease structures, and the relative affordability of most self-storage assets have made this niche especially appealing during a period of broader economic uncertainty. Month-to-month leases sound like a risk. In practice, they allow operators to raise rents more frequently than any long-term commercial lease ever would.
What the operating economics look like for small investors
The operating margin on storage units is a legitimate advantage over other real estate classes. The average net operating income margin for self-storage is 60 to 70%, and monthly rental rates in New York City can exceed $4.50 per square foot. Compare that with a traditional apartment building, where operating expenses regularly consume 40 to 50% of revenue.
Self-storage has proven resilient during tough times, including the 2008 financial crisis and the COVID-19 pandemic. Low operating costs and solid margins make it ideal for risk-averse investors. NAREIT data confirms that in 2008, most REITs suffered significant losses while self-storage posted a positive 5% return.
Large operators and REITs account for about 30% of the self-storage market in the U.S., with the rest controlled by independent owners. That fragmentation creates real acquisition opportunities for small investors who move before institutional consolidation reaches their target asset.
Expert perspective on the NYC storage investment opportunity
New York City is a market where the supply-demand math simply does not work in the renter’s favor, and that is precisely what makes it work in the investor’s favor. Occupancy rates above 90% give operators genuine pricing power. Month-to-month lease structures allow rent resets at a pace that no apartment or office lease permits. The fragmented ownership landscape means that a well-capitalized small investor can still acquire a facility at a price that institutional buyers would consider below the radar. The key discipline is underwriting realistic stabilization timelines. New facilities can take 3 years to fully lease up, so investors who underwrite for quick returns often misread the risk profile. The investors who perform consistently are the ones who buy constrained markets, manage costs tightly, and hold through the lease-up period.
Industry perspective, self-storage investment and commercial real estate professionals
How small investors enter the market
REITs and private equity firms need to acquire facilities to grow. The fragmented ownership structure means independent owners are the primary acquisition targets. The performance gap between institutional and independent operators is the real opportunity.
Rising interest rates and the need for liquidity have motivated many sellers to offer more competitive pricing and flexible terms, creating a favorable environment for buyers who want to expand their portfolios. A motivated seller in a supply-constrained borough is a rare combination that the current rate environment has made possible.
New development continues to face significant headwinds, including land and construction costs approximately 50% above pre-pandemic levels, tighter lending standards, and challenges in underwriting future rents. Consequently, despite permitting and zoning approvals, fewer projects are breaking ground, with annual supply growth projected at just 1.5% from 2025 to 2027. Limited new supply protects the returns of existing owners in ways that few other asset classes can guarantee.
Conclusion: storage units remain a serious position in an NYC portfolio
Cap rates have largely stabilized in 2024 and 2025 as the market adjusted to the higher rate environment. Self-storage remains one of the best-performing sectors in commercial real estate by virtually every measure. The investors who dismissed storage units as unglamorous real estate missed a cycle. The investors paying attention now have a second chance to position in a market where demand is structural, supply is legally constrained, and operating margins beat most alternatives. Storage units in New York City are not a trade. They are a hold, and the data supports that with clarity.
Discover more about storage units
- Self-Storage REITs: Sector Data, Returns and Investment Insights
- Q3 2025 Self-Storage Industry Report: Skyview Advisors
- Self-Storage Investment Surges as Sector Finds Its Floor: Yahoo Finance